Digital Arrest Scams Latest News
- On October 29, 2026, the Supreme Court urged the Reserve Bank of India (RBI) to introduce mandatory safeguards and make banks compensate victims of digital arrest frauds where institutional negligence or failure of due diligence is established.
Understanding Digital Arrest Scams
- Digital arrest is a form of cyber fraud in which criminals impersonate police officers, officials of central investigative agencies, judges or other government authorities through phone calls or video conferencing platforms.
- Fraudsters threaten victims with fabricated allegations of money laundering, financial irregularities or other criminal activities.
- They often use forged identity cards, official-looking documents and fake arrest warrants to create an atmosphere of fear and urgency.
- Victims are instructed to remain on video calls, avoid contacting family members and transfer money for purported verification, security deposits or settlement of cases.
- Digital arrest has no legal recognition in India. Law enforcement agencies do not arrest or detain individuals through video calls or demand money to prevent arrest.
Scale of Digital Arrest Frauds in India
- The scale of financial losses highlights the urgency of institutional intervention.
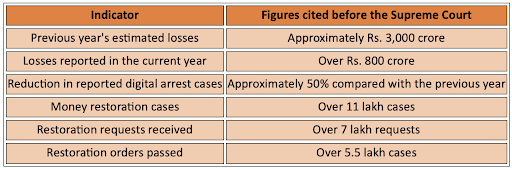
- The figures also demonstrate that public awareness campaigns alone cannot adequately address a fraud model that exploits institutional weaknesses and psychological manipulation.
Supreme Court's Intervention
- The Supreme Court has taken suo motu cognisance of the growing number of digital arrest frauds across the country.
- On October 29, 2026, a three-judge Bench comprising Chief Justice of India Surya Kant, Justice Joymalya Bagchi and Justice V. Mohana expressed serious concern over the scale of financial losses caused by these scams.
- The Court described digital arrest as one of the country's biggest financial frauds and questioned the delay in introducing stronger regulatory safeguards.
- The Bench also criticised the RBI for what it described as a slow response to the problem, particularly its continued consultations with banks despite the need for urgent preventive action.
Proposed Compensation and Bank Accountability
- The Supreme Court proposed directing banks to compensate victims where a failure of due diligence by the bank contributed to the fraud. It also raised the possibility of prosecution in cases involving institutional negligence or complicity.
- The Chief Justice emphasised that banks should be held accountable if suspicious transactions are allowed to proceed without adequate verification.
- The Court suggested that:
- Banks should temporarily suspend unusual transactions until mandatory verification protocols are completed.
- Suspicious transactions should trigger automated alerts and appropriate intervention.
- Financial institutions should be required to compensate victims where their failure to exercise due diligence is established.
- Accountability should extend to bank officials found involved in or negligent towards fraudulent transactions.
RBI's Proposed Regulatory Measures
- The Supreme Court examined the proposed Reserve Bank of India (Know Your Customer) Amendment Directions, 2026, intended to strengthen safeguards against cyber fraud.
- The Attorney General informed the Court that the RBI was in the advanced stages of finalising the regulatory framework. The proposed directions were expected to be notified by November 30 and operationalised by December 31, 2026.
- The proposed safeguards include:
- Transaction monitoring: Financial institutions should identify transactions that significantly deviate from an individual's established account history.
- Temporary suspension: Unusual transactions should be temporarily suspended until the prescribed verification process is completed.
- Automated alerts: Suspicious transactions should generate alerts for relevant police authorities.
- Physical verification: Authorities should undertake physical verification and establish the genuineness of suspicious transactions.
- Institutional accountability: Banking officials and financial institutions should be subject to appropriate accountability mechanisms where negligence or complicity is established.
Role of Technology Platforms and Law Enforcement Agencies
- Digital arrest scams frequently exploit instant messaging platforms, particularly WhatsApp, to impersonate government officials and maintain prolonged contact with victims.
- During the hearing, WhatsApp informed the Court that it had independently banned approximately 9,400 suspicious accounts.
- The Attorney General also informed the Court that the responsibilities of digital intermediaries would form part of instructions being developed by the Ministry of Electronics and Information Technology (MeitY) and the Department of Telecommunications.
- The Bench further directed State governments to submit details of FIRs registered in digital arrest cases, along with the status of investigations and prosecutions.
Challenges in Combating Digital Arrest Frauds
- Despite increasing awareness and regulatory intervention, several challenges remain:
- Psychological manipulation: Fraudsters exploit fear of arrest, social stigma and the authority associated with law enforcement institutions.
- Institutional gaps: Delayed detection of unusual transactions can allow stolen funds to be transferred rapidly across multiple accounts.
- Jurisdictional complexity: Cyber fraud networks may operate across multiple States and jurisdictions, complicating investigation and prosecution.
- Digital impersonation: Forged documents, official identities and manipulated video calls make scams appear credible.
- Delayed recovery: Once funds are transferred through multiple accounts, tracing and recovering the money becomes difficult.
- The problem requires coordinated action involving banks, the RBI, police authorities, digital platforms and central government agencies.
Digital Arrest Scams FAQs
Q1: What is a digital arrest scam?
Ans: It is a cyber fraud in which criminals impersonate law enforcement officials through calls or video conferencing and threaten victims into transferring money.
Q2: Can a person be arrested through a video call in India?
Ans: No. Digital arrest has no legal recognition in India. Police and investigative agencies do not arrest individuals through video calls or demand money to avoid arrest.
Q3: What has the Supreme Court proposed regarding bank liability?
Ans: The Court proposed making banks compensate victims where failure of due diligence contributed to the fraud, alongside possible prosecution in appropriate cases.
Q4: What are the RBI's proposed KYC Amendment Directions, 2026?
Ans: They are proposed regulatory measures intended to strengthen transaction monitoring, verification and institutional safeguards against cyber fraud.
Q5: What role does WhatsApp play in combating digital arrest scams?
Ans: WhatsApp informed the Supreme Court that it had banned approximately 9,400 suspicious accounts and was developing software to identify accounts impersonating law enforcement officials and government agencies.